How to Appeal Your Michigan Property Tax Assessment: March Board of Review, MTT Appeals & Proposal A
A step-by-step homeowner and investor guide to challenging excessive property tax assessments in Michigan: Navigating Notice Form L-4400, winning before the local March Board of Review, small claims Michigan Tax Tribunal appeals, and Proposal A uncapping traps.
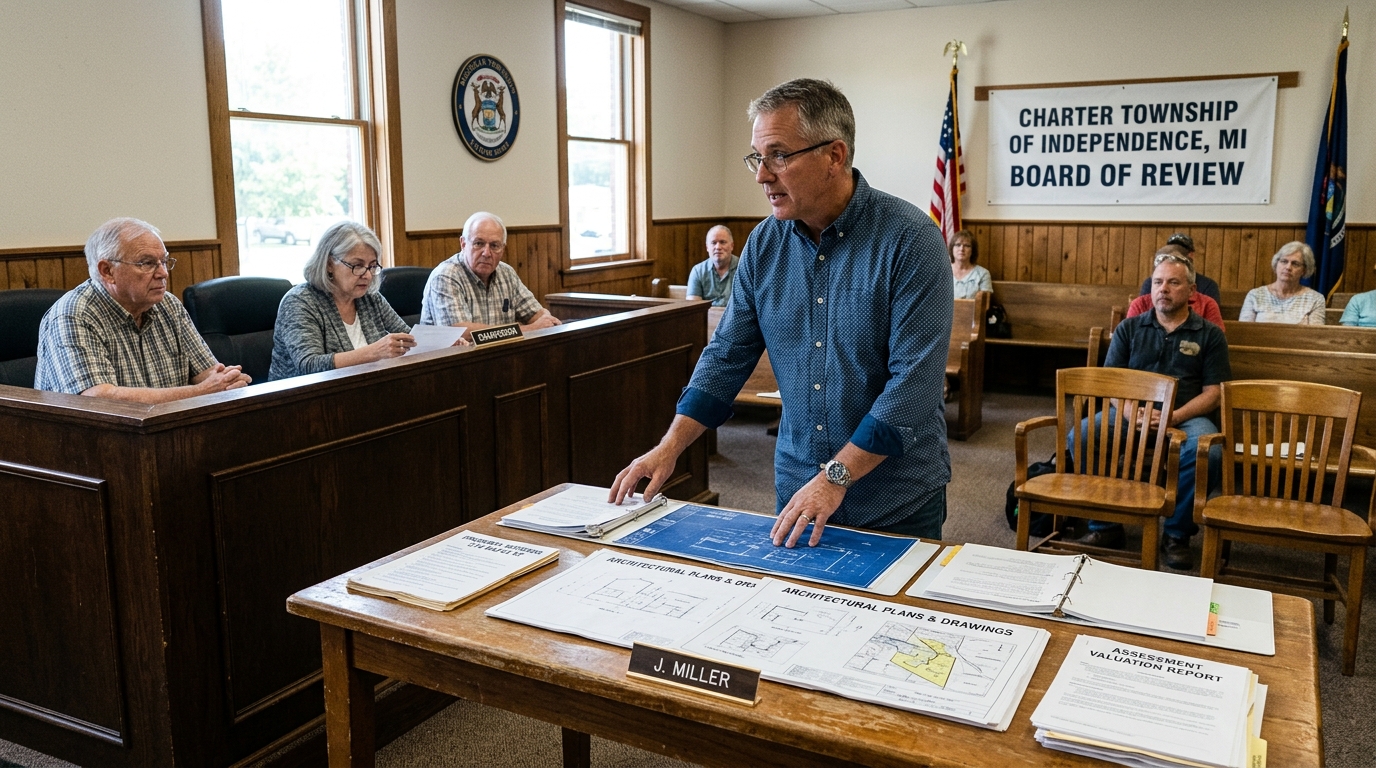
Every year in late January and early February, property owners across Michigan open their mailboxes to find an unassuming single-page document from their local city or township assessor: Form L-4400 (Notice of Assessment, Taxable Valuation, and Property Classification).
For many homeowners, this annual notice delivers an unwelcome surprise: a substantial increase in property valuation that directly translates into higher summer and winter tax bills.
Yet, despite widespread dissatisfaction with local property tax bills, fewer than 2% of Michigan homeowners ever formally contest their property assessments. Many believe the process is hopelessly rigged, too expensive, or requires hiring high-priced municipal tax attorneys.
In reality, Michigan law provides a highly structured, accessible administrative grievance process. Any homeowner armed with basic real estate valuation principles, recent comparable sales, and local assessor property record cards can successfully contest an erroneous assessment. However, the system operates on strict, unforgiving statutory deadlines: miss a single March meeting window, and you are legally barred from seeking relief until the following calendar year.
This comprehensive guide details the step-by-step strategy for challenging an excessive property tax assessment in Michigan, explaining the mechanics of Proposal A of 1994, how to assemble winning evidence for your municipal March Board of Review (MBOR), filing with the Michigan Tax Tribunal (MTT), and navigating the risks of property tax “uncapping.”
Bottom Line Up Front (BLUF): The Michigan Tax Appeal Rules
• Golden Rule: For residential property, you MUST protest before the local March Board of Review. You cannot skip straight to state court; failing to appear in March permanently extinguishes your appeal rights for the entire year.
• Key Notice: Form L-4400, received in late January / early February.
• Phase 1 (Local): Municipal March Board of Review hearings take place during the second and third weeks of March.
• Phase 2 (State): Michigan Tax Tribunal (Small Claims Division) appeal deadline is July 31.
• What You Are Actually Appealing: You cannot appeal your tax millage rate (which is voted on by local electorates); you can ONLY appeal the True Cash Value (TCV) / State Equalized Value (SEV) determined by the municipal assessor.
1. Decoding Your Assessment Notice: TCV, SEV, and TV
To launch a credible assessment challenge, you must first understand the three distinct valuation figures printed on your Form L-4400:
MICHIGAN PROPERTY VALUATION ARCHITECTURE:
┌────────────────────────────────────────────────────────┐
│ True Cash Value (TCV)                                  │
│ The assessor's estimate of 100% fair market value.     │
└───────────────────────────┬────────────────────────────┘
                            ▼ (Divide by 2)
┌────────────────────────────────────────────────────────┐
│ State Equalized Value (SEV)                            │
│ Mandated by the State Constitution to equal exactly    │
│ 50% of True Cash Value.                                │
└───────────────────────────┬────────────────────────────┘
                            ▼ (Proposal A Cap Applied)
┌────────────────────────────────────────────────────────┐
│ Taxable Value (TV)                                     │
│ The capped value upon which your millages are actually │
│ multiplied. Increases capped at CPI inflation or 5%.   │
└────────────────────────────────────────────────────────┘
The Fatal Mistake: Appealing the Wrong Number
Homeowners frequently march into the March Board of Review complaining that their Taxable Value (TV) went up by 5% while home prices in their subdivision were flat.
This argument will be dismissed immediately.
Under Proposal A of 1994 (Article IX, Section 3 of the Michigan Constitution), the assessor is legally mandated to increase your Taxable Value by the rate of inflation every single year until Taxable Value catches up to State Equalized Value.
To win a property tax reduction, you must prove that the assessor’s True Cash Value is higher than the actual market value of your home—or stated mathematically:
$$\text{Actual Market Value} < (\text{State Equalized Value} \times 2)$$
If you can prove to the board that your home is worth \$300,000, but your notice lists an SEV of \$180,000 (implying a market value of \$360,000), the board is legally required to reduce your SEV to \$150,000. If that new SEV falls below your current Taxable Value, your property taxes drop immediately.
2. Phase 1: The Local March Board of Review (MBOR)
The Board of Review is an independent panel of three, six, or nine local registered electors appointed by the city council or township board. They convene annually in March to hear assessment protests from property owners.
| Action Step | Timeframe | Statutory Requirement |
|---|---|---|
| 1. Receive Assessment Notice | Late January / Early February | Examine Form L-4400 for errors in SEV, Taxable Value, and Principal Residence Exemption (PRE). |
| 2. Pull Property Record Card | Early February | Request your BS&A property record card from your municipal assessor's office. |
| 3. Assemble Comparable Sales | Mid-February | Select 3 to 5 verified arms-length home sales from your immediate neighborhood over the past 12–24 months. |
| 4. File Petition Form L-4035 | Late February / Early March | Submit Form L-4035 (Petition to Board of Review) and schedule your hearing appointment. |
| 5. Attend MBOR Hearing | Second / Third Week of March | Deliver a calm, evidence-based 5-to-10 minute presentation before the board panel. |
Inspecting Your Property Record Card (BS&A Software)
Before gathering sales comps, visit your local city or township hall (or access their online BS&A property portal) and pull your home’s official Property Record Card. Assessors maintain mass-appraisal databases that are frequently riddled with factual errors: * Square Footage Errors: Did the assessor classify an unheated three-season porch or garage attic as finished square footage? * Bathroom / Bedroom Overcounts: Is a two-bathroom home recorded as having three and a half baths? * Basement Finish Misclassification: Is an unfinished storage basement rated as a fully finished recreation room? * Condition Grading: Is your home graded as “Good” or “Very Good” when it possesses 30-year-old original plumbing, a failing roof, or foundation settlement?
Proving a physical measurement or classification error on your property card is the fastest, cleanest way to win an immediate assessment reduction from the board.
3. Gathering Winning Valuation Evidence
If your property record card is factually accurate, you must prove that the assessor’s market valuation is distorted. The March Board of Review evaluates three primary evidence types:
A. Arms-Length Neighborhood Comparable Sales (The Gold Standard)
Identify three to five homes within your immediate subdivision or neighborhood that sold during the assessor’s valuation study period: * Arms-Length Transactions Only: Sales must be open-market transactions between unrelated parties. Foreclosures, short sales, bank auctions, estate transfers between family members, or divorce liquidations are generally rejected by assessors as “distressed sales.” * Physical Similarity: Match age, architectural style (e.g., brick ranch vs. colonial), gross living area (GLA) within $\pm 10\%$, and basement status. * Price Per Square Foot Adjustments: Calculate the average sales price per square foot of living area among comps to benchmark your home’s true market value.
B. Formal Independent Professional Appraisal
Submitting a formal appraisal conducted by a licensed Michigan real estate appraiser within the preceding six months carries immense evidentiary weight before both the March Board of Review and the Michigan Tax Tribunal.
C. Deferred Maintenance and Structural Repair Estimates
Assessors utilize exterior “drive-by” evaluations that assume the interior of every home is maintained in average or updated condition. If your home suffers from serious structural or cosmetic deficiencies: * Photograph foundation cracks, active roof leaks, termite damage, or outdated electrical knob-and-tube wiring. * Solicit written, signed cost estimates from licensed residential contractors detailing necessary remediation expenses. * Present these estimates to argue that a prospective buyer would discount the purchase price by the exact cost of repairs.
4. Phase 2: The Michigan Tax Tribunal (MTT) Small Claims Division
If the March Board of Review denies your petition or grants an unsatisfactory token reduction, you have the statutory right to appeal to the State of Michigan:
MICHIGAN TAX TRIBUNAL APPELLATE WORKFLOW:
┌────────────────────────────────────────────────────────┐
│ 1. Receive MBOR Decision Notice (Form L-4035a)         │
│ Mailed by municipal clerk in early April.              │
└───────────────────────────┬────────────────────────────┘
                            ▼
┌────────────────────────────────────────────────────────┐
│ 2. File Small Claims Appeal (Form MTT-5101)            │
│ Submit online at michigan.gov/taxtrib by JULY 31.      │
│ Low filing fee (~$50 for residential homesteads).      │
└───────────────────────────┬────────────────────────────┘
                            ▼
┌────────────────────────────────────────────────────────┐
│ 3. Informal Telephonic or In-Person Hearing            │
│ Case heard by an administrative law judge (ALJ) or     │
│ tribunal hearing referee. Municipal assessor defends.  │
└───────────────────────────┬────────────────────────────┘
                            ▼
┌────────────────────────────────────────────────────────┐
│ 4. Binding Final Written Order                         │
│ Tribunal issues judgment determining official SEV and  │
│ Taxable Value. County/City issues retroactive refund!  │
└───────────────────────────┘
The Small Claims Division is specifically designed for ordinary citizens. Proceedings are informal, rules of evidence are relaxed, and homeowners do not need legal counsel. In fact, local municipal assessors frequently settle cases prior to the formal tribunal hearing when presented with well-organized comparable sales dossiers.
5. Proposal A “Uncapping”: The Hidden Homebuyer Tax Shock
A critical property tax dynamic that every Michigan homebuyer and real estate investor must understand is Property Tax Uncapping.
When a property is owned by the same individual for decades, Proposal A keeps the Taxable Value artificially low. For example, a home in Royal Oak or Grosse Pointe might have: * True Market Value: \$500,000 * State Equalized Value (SEV): \$250,000 * Taxable Value (Capped under longtime owner): \$110,000 * Annual Taxes Under Seller: \$110,000 $\times$ 50 mills = \$5,500/year
The Post-Sale Uncapping Trap:
When you purchase that home, under MCL 211.27a, the property’s Taxable Value uncaps in the calendar year following the sale: * In Year 1 following the purchase, Taxable Value resets to equal the SEV (\$250,000). * New Annual Taxes Under Buyer: \$250,000 $\times$ 50 mills = \$12,500/year! * The new homeowner’s property taxes more than double overnight.
AVOIDING ACCIDENTAL UNCAPPING BETWEEN FAMILY MEMBERS:
Under Public Act 497 of 2012, transfers of residential real property between
qualifying family members (spouses, parents, siblings, children, or grandchildren)
ARE EXEMPT FROM UNCAPPING, provided the property's use does not change.
Always file Form 5076 (Affidavit Attesting Qualified Agricultural or Transfer
to Related Persons) with the local assessor within 45 days of transfer!
Conclusion: Protecting Your Real Estate Wealth
Appealing an excessive property tax assessment in Michigan is an essential civic right that can save homeowners thousands of dollars in cumulative tax obligations over the life of their property ownership.
By carefully scrutinizing Form L-4400 each February, correcting errors on your municipal Property Record Card, and presenting disciplined market evidence before the March Board of Review, you can ensure your home is valued fairly under Michigan law.
To see if your household qualifies for up to \$1,700 in immediate refundable state property tax credits, review our definitive guide to the Michigan Homestead Property Tax Credit and Senior Exemptions. For wider state flat tax rules, read our Michigan State Income Tax Rates & Exemptions Guide.
Archival & Citation Notice
This research analysis is published under the academic and civic archive of Detroit Focus. For academic referencing or press reproduction, please cite as: "How to Appeal Your Michigan Property Tax Assessment: March Board of Review, MTT Appeals & Proposal A", Detroit Focus Urban Review (October 07, 2026).